[Edaily Reporter KIM SAE-MI ] Voronoi, Inc.(310210)has granted its Chief Medical Officer (CMO), a former Eli Lilly executive, extraordinary stock options that can only be exercised if a change in control occurs when the company’s valuation exceeds 30 trillion won. Observers note that this effectively serves as an “M&A success bonus,” as the company is reportedly aiming to boost the value of its core pipeline with an eye toward potential management control transactions, such as global mergers and acquisitions (M&A).
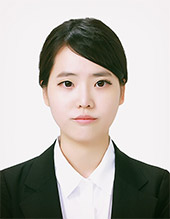
Yin Zhang, Chief Medical Officer (CMO) of Voronoi, Inc. (Photo: Voronoi, Inc.)
Stock Options Vested Only Upon Achieving Both “Market Cap of 30 Trillion Won” and “Sale of Controlling Interest”
According to the Financial Supervisory Service’s electronic disclosure system on the 10th, Voronoi, Inc. announced the previous day that it had granted stock options to CMO Yin Zhang and issued a corrected disclosure at 10:21 a.m. that day.
The previous day’s disclosure revealed that Voronoi, Inc. had granted CMO Yin Zhang stock options for 129,100 common shares, with an exercise price of 200,000 won per share and an exercise period from September 10, 2028, to September 9, 2038. Apart from the condition that the recipient must be employed by Voronoi, Inc. or its U.S. subsidiary (Voronoi Inc. U.S.) at the time of exercise, no specific vesting requirements were specified. Vesting requirements refer to the conditions that must be met in order to actually exercise the stock options.
Voronoi, Inc. specified that the vesting conditions for the stock options granted to CMO Jang In include a merger or acquisition (M&A) involving a change in control and the achievement of an enterprise value between 30 trillion and 100 trillion won. (Source: Financial Supervisory Service Electronic Disclosure System)
The vesting conditions disclosed in this amended filing are unusual. A “merger or acquisition involving a change in control” must occur, and the vesting schedule is as follows: 105,000 shares upon reaching an enterprise value of 30 trillion won, 114,130 shares at 40 trillion won, and 119,320 shares at 50 trillion won. The full 129,100 shares are vestable only when the enterprise value reaches 100 trillion won.
Voronoi, Inc. explained, “The actual contract between CMO Jang and the company was concluded with ‘and’ conditions—namely, enterprise value and a change in controlling interest,” adding, “The initial disclosure was submitted in accordance with the prescribed format, and the full allocation requirements were added later.”
The company clarified that the enterprise value cited in the disclosure is based on market capitalization. According to Korea Exchange (KRX) data, Voronoi, Inc.’s market capitalization as of the previous day (the 9th) was approximately 3.416 trillion won; 30 trillion won would be 8.8 times its current value. As of today (the 10th), the only domestic biotech companies with a market capitalization exceeding 30 trillion won are SAMSUNG BIOLOGICS(207940)(65.872 trillion won) and Celltrion(068270)(42.0527 trillion won). The third-ranked company, Alteogen Inc.(196170), has a market capitalization of 19.2945 trillion won. No domestic biotech company has yet surpassed the 100 trillion won market capitalization threshold set by Voronoi, Inc. as a full fulfillment condition.
Assuming, for simplicity’s sake, that the number of listed shares remains at current levels, if the market capitalization reaches 30 trillion won, Voronoi, Inc.’s stock price would be approximately 1.29 million won. If CMO Jang exercises 105,000 shares at this price, the potential profit—excluding the exercise price—would amount to approximately 114.1 billion won. For the market capitalization to reach 100 trillion won, Voronoi, Inc.’s stock price would need to rise to 4.29 million won. If all 129,100 shares were exercised at that price, the potential profit would amount to 527.8 billion won.
It is important to note that simply increasing the company’s enterprise value is not sufficient to exercise this option. Voronoi, Inc. stated, “Both an enterprise value of over 30 trillion won and a change of control by the largest shareholder must occur,” adding, “Even if the enterprise value reaches 30 trillion won, the option cannot be exercised if CEO Kim Hyun-tae retains control.”
According to the company, such a change in control refers to a situation where CEO Kim loses control of the company and it passes to a third party, and this can take various forms, such as M&A or attracting strategic investors (SIs). A Voronoi, Inc. official explained, “A ‘Change of Control’ refers to any event in which CEO Kim Hyun-tae loses control of the company and transfers it to another party.”
The key point is that this requires a substantive transfer of management control—not merely the sale of a portion of shares or the attraction of a small-scale strategic investor. In other words, for CMO Jang to actually receive his massive stock option compensation, he must not only drive an increase in the company’s value but also facilitate the transfer of management control from CEO Kim, the largest shareholder.
Although these are extraordinary stock options that could yield compensation in the hundreds of billions of won, the risk borne by the company and the largest shareholder is not significant. This is because, by the time both conditions are met, the company’s value will have risen substantially, and the largest shareholder can also expect significant exit gains through the sale of management control. As of the 31st of last month, CEO Kim Hyun-tae, the largest shareholder, held 6,632,019 shares of Voronoi, Inc. (a 34.99% stake). Assuming the number of shares remains unchanged, the value of that stake would amount to 8.533 trillion won at a market capitalization of 30 trillion won, and 28.442 trillion won at 100 trillion won.
A biotech industry insider noted, “While the size of the stock options alone is enormous, to actually receive this level of compensation, the market capitalization must exceed 30 trillion won and the transfer of management control must be finalized,” adding, “For the company, this is a structure that allows it to demonstrate confidence in its enterprise value growth and a commitment to M&A without immediately injecting cash, while also carrying very little risk.”
For the Commercialization of Key Pipeline Products… Would the Largest Shareholder Sell Control?
So why did Voronoi, Inc. design this structure? Voronoi, Inc. explained that it is because the company is keeping strategic options—including global joint development and M&A—in mind, rather than insisting solely on independent development of its key pipeline products, “VRN10” and “VRN11.”
This is interpreted as a willingness to even sell the controlling stake held by the largest shareholder if it means commercializing VRN10 and VRN11. Although Voronoi, Inc. is currently conducting global clinical trials for these two drug candidates on its own, the company recognized that there are limitations to carrying out everything from late-stage clinical trials to commercialization independently. Accordingly, the company’s policy is to maximize the value of the drug candidates through in-house development and then pursue joint development with global pharmaceutical companies or, if necessary, keep the door open to a management control transaction via M&A.
Voronoi, Inc. official stated, “While we can maximize value through our own R&D capabilities up to the preclinical and early clinical stages, the late-stage global clinical trials and commercialization phases are costly and require compliance with regulations in various countries, making it difficult for a small domestic biotech company to handle everything on its own.” The official added, “Whether through joint development, strategic investment, or M&A, we are keeping all strategies open that will maximize the drug’s value upon commercialization.”
However, the company made it clear that no M&A negotiations with global pharmaceutical or biotech companies are currently underway. A Voronoi, Inc. representative said, “We are not currently in the stage of actively negotiating an acquisition with a global pharmaceutical company,” but added, “Whenever management meets with global Big Pharma, we intend to keep these strategic options open.”
Who Is CMO Jang, Who Accepted These Unprecedented Terms? ‘Formerly of Lilly’s Clinical Development Division’
So, who is CMO Jang, and why did he accept these terms to take on such a crucial role? CMO Jang is a new drug clinical development expert who previously served as Vice President of Global Clinical Development at Loxo@Lilly, the oncology development unit of global pharmaceutical company Eli Lilly. At Lilly, he led numerous global oncology clinical programs, gaining extensive development experience spanning from early- to late-stage clinical trials.
Since joining Voronoi, Inc., he has been overseeing global clinical development strategy, with a focus on the U.S. organization. In particular, he is responsible for the global clinical progress and patient safety of the company’s core pipeline candidates: VRN11, a treatment for EGFR-mutated non-small cell lung cancer, and VRN10, a treatment for HER2-mutated solid tumors. He has thus assumed a pivotal role in Voronoi, Inc.’s strategy to advance its internally discovered candidates to the global late-stage clinical and commercialization phases.
Currently, VRN11 is expanding into global Phase 1b and 2 clinical trials for EGFR-mutated non-small cell lung cancer. VRN10 is undergoing a Phase 1a dose-escalation trial for HER2-mutated solid tumors. Given that the clinical outcomes of these pipeline candidates and their global commercialization will determine Voronoi, Inc.’s corporate value, CMO Jang’s role is bound to be significant.
A Voronoi, Inc. spokesperson remarked, “The very fact that CMO Jang agreed to a stock option contract under these terms suggests he has considerable confidence in the successful development of Voronoi, Inc.’s core pipelines and the growth of the company’s enterprise value.”
SamsungElectronics will showcase a heat pump solution that uses electricity to provide heating, cooling, and hot water at the “2026 Green Hydrogen Global Forum” being held in Jeju. As the electrificat…
Ottogi(007310)marked the 10th anniversary of the passing of its founder, the late Honorary Chairman Ham Tae-ho, by reflecting on its management philosophies of “quality first” and “sharing.” OTOKI Cha…
Samsung SDS (SAMSUNG SDS CO., LTD.(018260)) has been ranked No. 1 globally in the “Software & Telecommunications” category of Newsweek’s “World’s Most Trusted Companies 2026” list.Samsung SDS announce…